
1. Introduction
After storm damage, a contractor offering to "take care of your deductible" can sound like they're saving you money.
But that's probably not the most important thing a roofer can bring to an insurance-related roofing project.
A good roofing contractor should help you understand what's actually wrong with the roof, document the damage clearly, develop an accurate estimate for the work, and provide the information your insurance adjuster may need to evaluate the roofing portion of the claim.
Your deductible is part of your insurance policy. Instead of choosing a roofer based on who promises to make it disappear, look closely at what the contractor can actually contribute to the claim and the roof itself.
2. Start With the Roof, Not the Deductible
The first conversation should be about the condition of your roof.
What was damaged? Where is the damage located? Is the problem limited to one area or spread across the roofing system? What repair or replacement work does the contractor believe is necessary?
A reputable roofer should be able to walk you through those findings and, when possible, show you photographs or other documentation.
That's much more useful than immediately turning the conversation into a pitch about what the project will supposedly cost you out of pocket.
Before talking about how the claim will be paid, make sure you understand what you're asking the insurance company to pay for.
3. A Good Roofing Estimate Can Matter During the Claim
The contractor's estimate does more than tell you the price of the job.
For an insurance-related project, it can help clearly describe the roofing work the contractor believes is necessary.
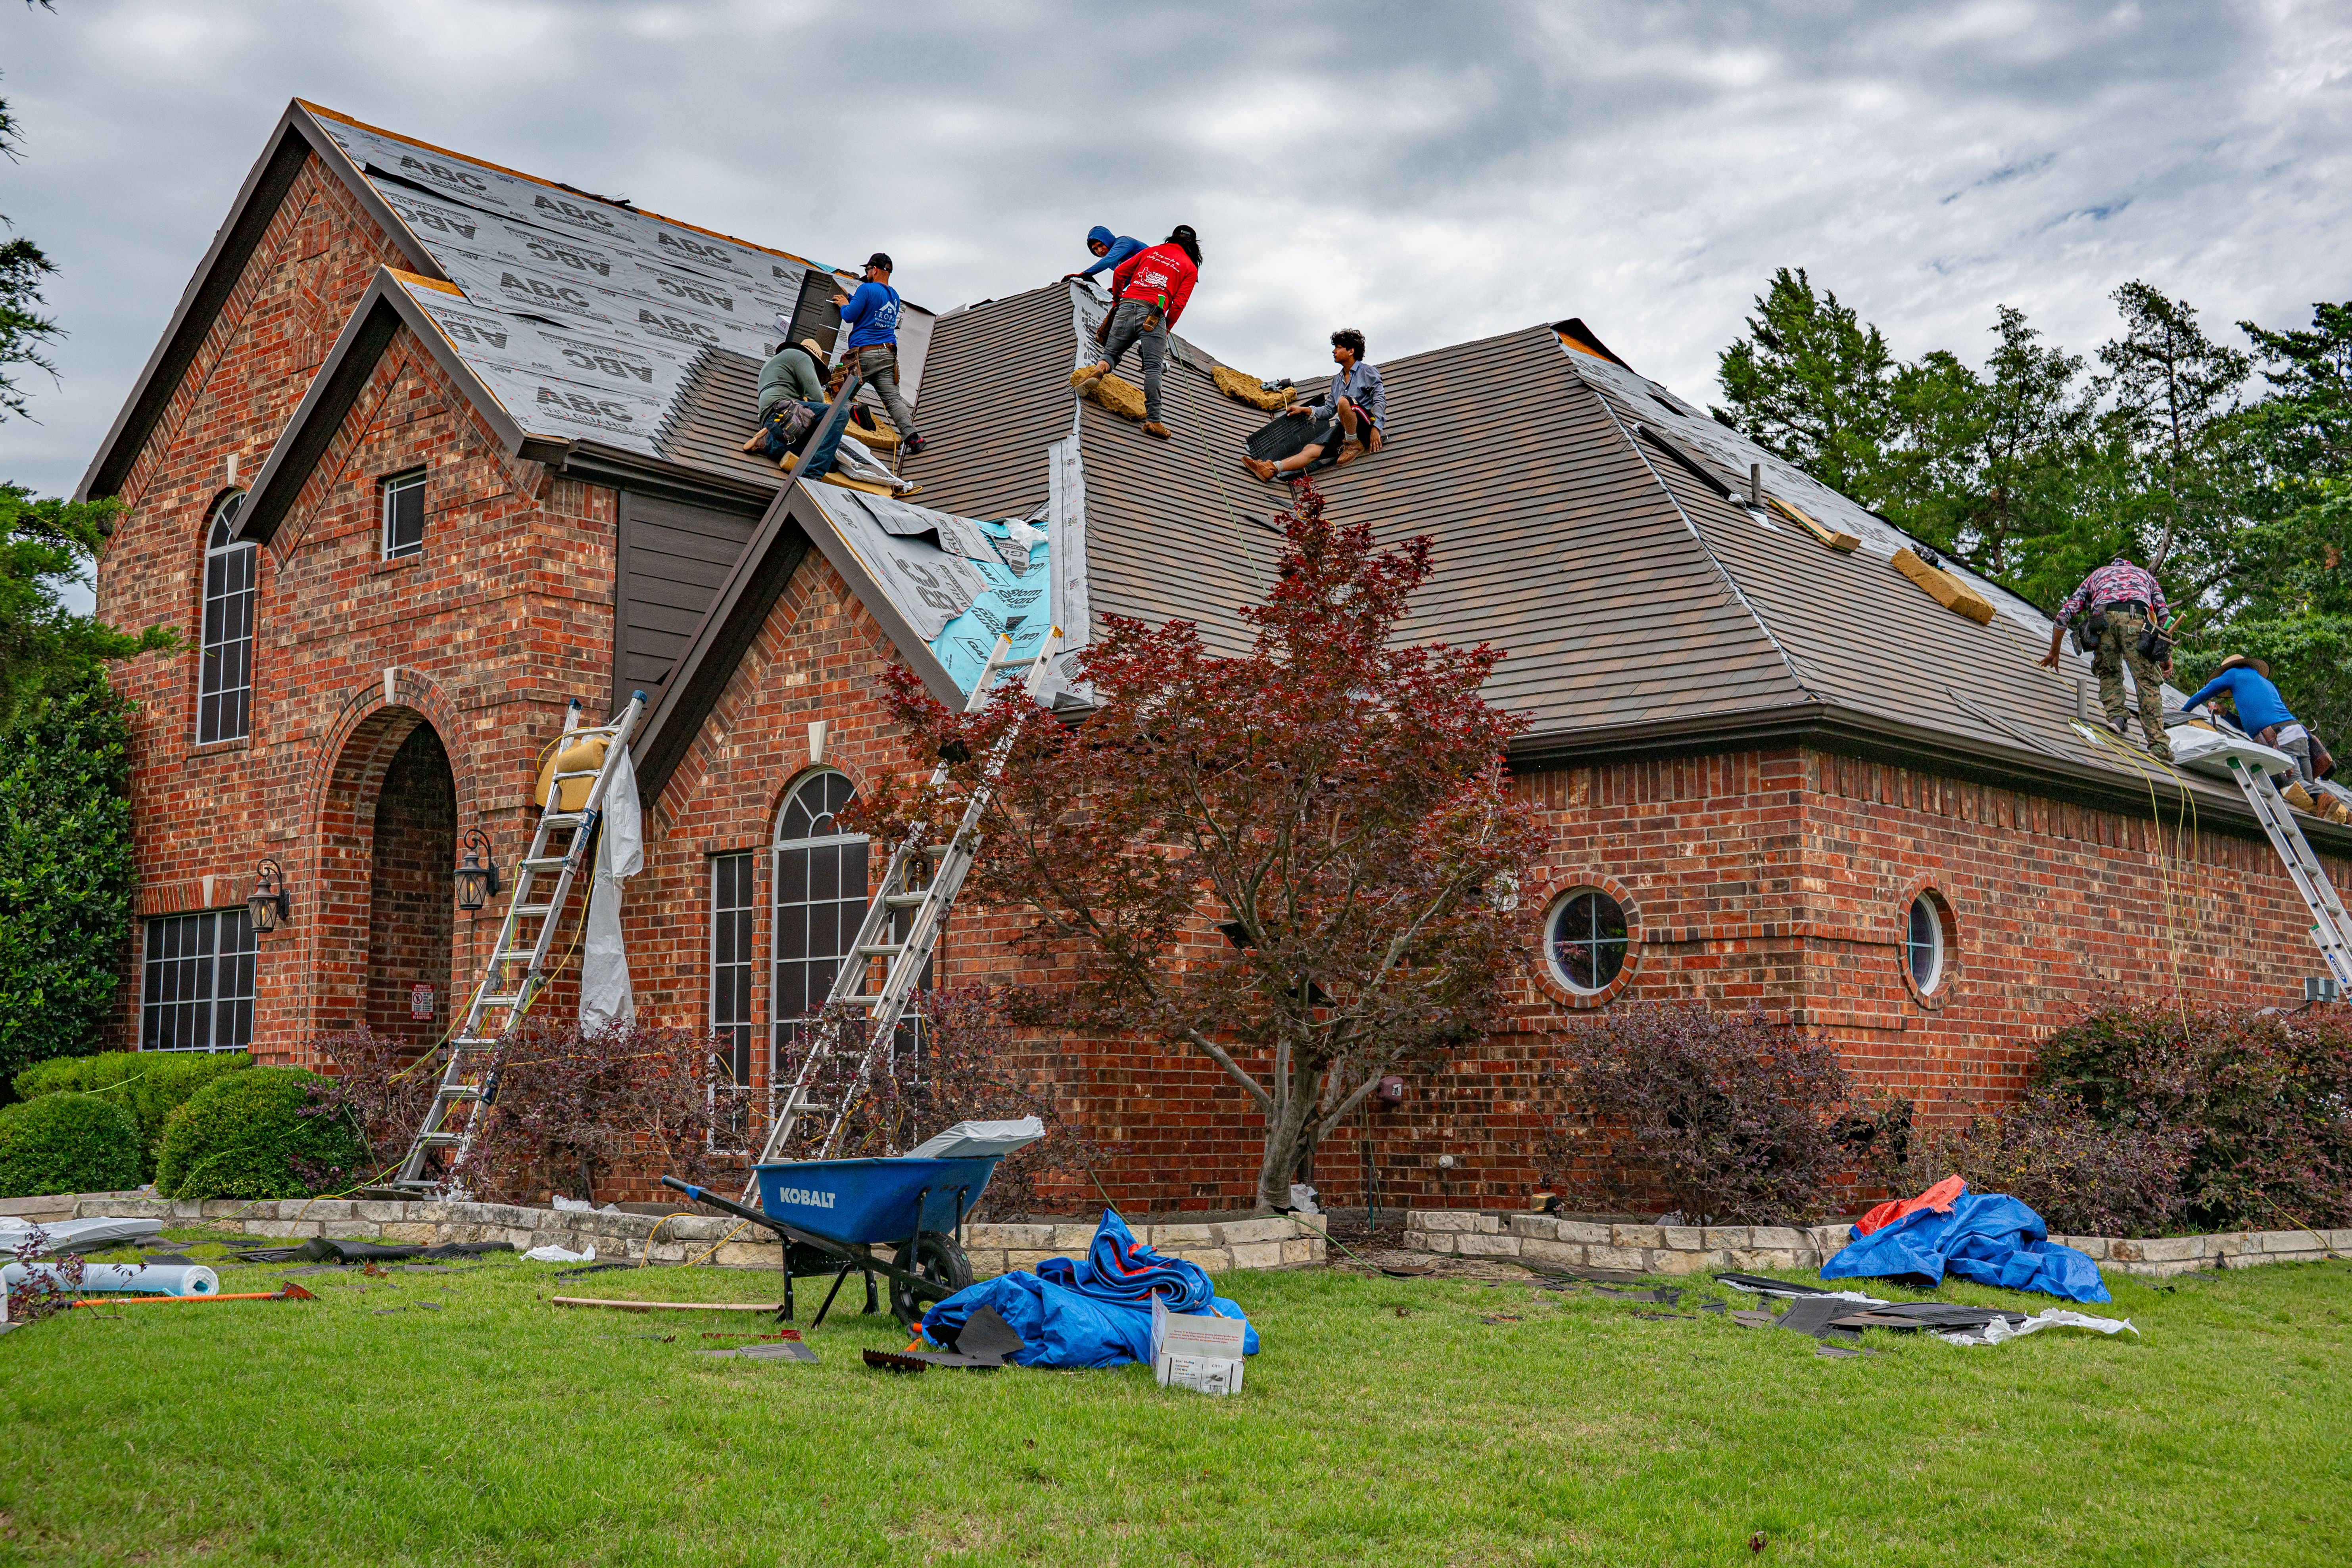
That may include the damaged roofing materials, removal and replacement work, underlayment, flashing, disposal, labor, and other project-specific items.
A detailed estimate gives the adjuster something concrete to review rather than leaving the roofing scope vague.
4. Your Roofer and Adjuster May See Different Things
An insurance adjuster evaluates the claim for the carrier. A roofer evaluates what they believe is needed to properly address the roof.
Those assessments may not always line up perfectly the first time.
Maybe the roofer identifies flashing that needs to be replaced as part of the repair. Maybe additional damage becomes visible once roofing materials are removed. Maybe the contractor's scope includes roofing components that weren't obvious during the original insurance inspection.
That doesn't automatically mean either side is acting improperly.
What matters is whether the contractor can clearly document why the work is necessary and provide that information for the claim to be reviewed.
If hidden damage is discovered after the original adjustment, contact the insurer so the difference can be addressed.
5. Look for a Contractor Who Can Explain Their Estimate
A good roofer shouldn't simply hand over a large number and expect everyone else to figure it out.
They should be able to explain how the estimate relates to the actual roof.
If an adjuster or homeowner has a question about a roofing line item, the contractor should be able to explain what it represents and why it was included.
That can be particularly important when several parts of the roofing system work together. Removing damaged material may affect flashing, underlayment, penetrations, or adjoining roofing areas.
The contractor's job isn't to decide what your insurance policy covers. That's the insurer's responsibility.
Their job is to accurately represent the roofing work they believe the property requires.
6. Ask What Happens If Something Was Missed
Some damage isn't visible during the initial inspection.
Once existing roofing materials come off, the contractor may discover deteriorated decking or another condition that changes the work required.
Before the project begins, ask how your roofer handles that situation.
Will they stop and document what they found? Will they photograph it? Will they prepare an updated estimate or additional information that can be submitted for review when appropriate?
A contractor who understands insurance-related roofing work should have a process for documenting legitimate changes rather than simply adding unexplained charges later.
7. The Best Offer Isn't Always the Biggest Discount
This is where the deductible pitch can become distracting.
Imagine choosing between one contractor who promises to "eat your deductible" and another who thoroughly inspects the roof, documents the damage, explains the proposed work, prepares a detailed estimate, answers questions about the roofing scope, and stays involved when additional roofing information is needed.
The second contractor may ultimately provide far more value.
Your priority should be getting the roof properly evaluated and having the legitimate work represented as clearly as possible.
A vague promise about your deductible doesn't tell you whether the contractor will do any of that well.
8. Keep Your Own Interests at the Center of the Claim
Your roofer works on roofs. Your insurer evaluates coverage. You are the property owner living with the result.
That means you should understand what's happening at each stage.
Ask the roofer to explain the damage. Review the estimate. Read the insurer's documents. Ask questions when the scopes don't appear to match.
You don't need to become a roofing or insurance expert, but you should never feel like important decisions are happening around you without explanation.
The best contractors help make the process clearer.
9. Look Beyond the Deductible Pitch
If a roofer's biggest selling point is that you won't have to worry about your deductible, ask what else they're bringing to the table:
Can they clearly document the damage?
Can they prepare a detailed roofing estimate?
Can they explain why each part of the work is needed?
Can they provide additional roofing documentation if hidden conditions are discovered?
Will they stay available to answer roofing questions throughout the claim and project?
Those answers tell you much more about the contractor you're considering.
Professional Roofing Services has served the Las Vegas Valley for more than 40 years and provides storm damage inspections and repairs for residential and commercial properties. When insurance is involved, PRS can inspect the roofing system, document relevant conditions, prepare a detailed roofing estimate, and provide roofing information needed for the claim review process.
If storm damage has left you wondering what your roof needs, contact PRS for an inspection and a clearer understanding of the work before deciding how to move forward.
10. Frequently Asked Questions (FAQs)
What can a roofing contractor provide for an insurance claim?
A roofer can inspect the roofing system, document visible damage, take photographs, prepare a detailed estimate, explain the recommended roofing work, and provide additional roofing information when appropriate. Your insurance carrier and adjuster remain responsible for determining what the policy covers and how the claim will be paid.
Why does the roofer's estimate matter if the adjuster already inspected the roof?
The two professionals have different roles. An adjuster evaluates the insurance claim, while the roofing contractor determines what work they believe is necessary to complete the roofing project. A contractor's detailed estimate can help identify and explain roofing components or work included in the proposed repair.
What happens if a roofer discovers more damage after work begins?
Some conditions aren't visible until existing roofing materials are removed. The contractor should document what was found and explain any additional work required. When the project involves an insurance claim, that information may need to be provided to the insurer for further review before additional covered work is approved.
Can PRS work with my insurance adjuster?
PRS can provide roofing documentation, estimates, photographs, and information explaining the roofing work being recommended. PRS's role is to accurately document and explain the roofing scope, while your insurance carrier remains responsible for evaluating coverage and making claim decisions.